
Debt Restructuring and Personal Bankruptcy in Singapore: The 2026 Guide
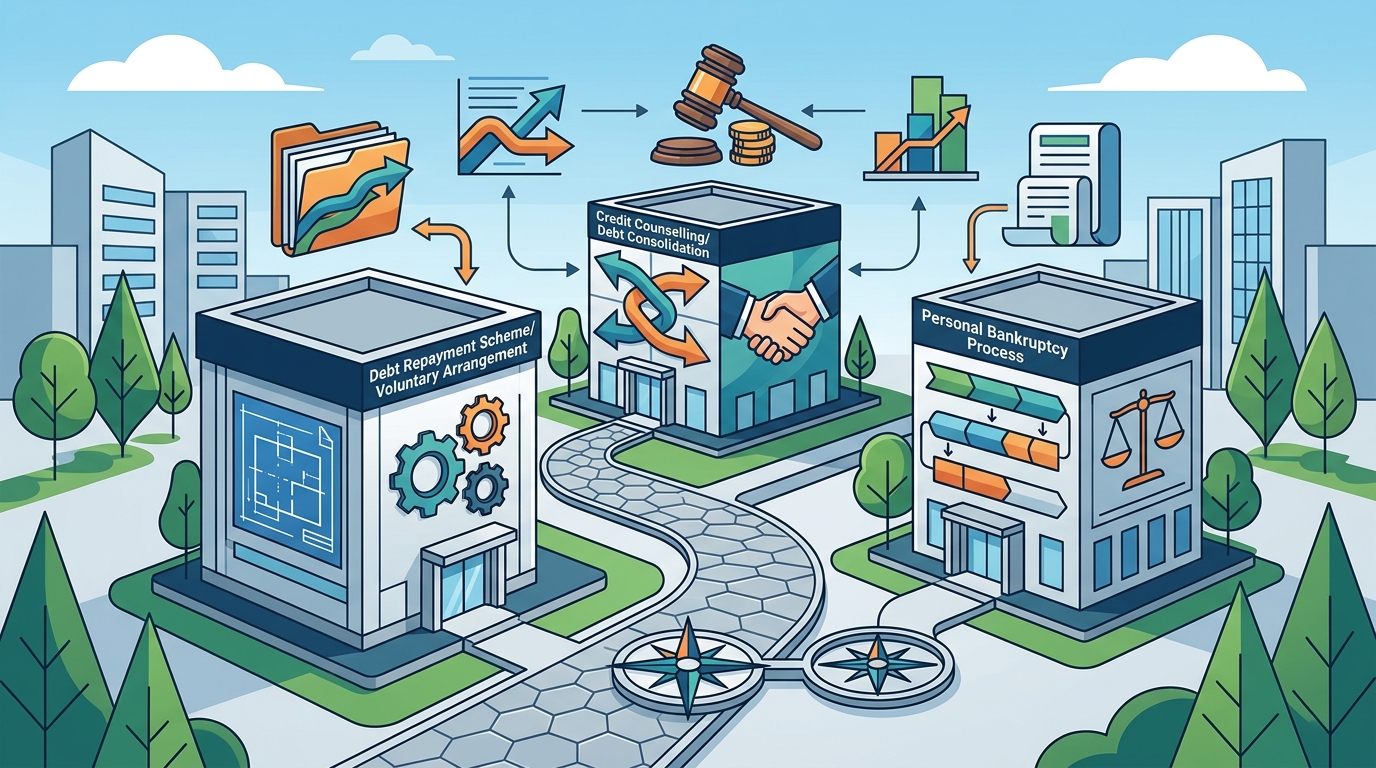
Debt restructuring in Singapore is the legal process of renegotiating repayment terms to avoid insolvency. For individuals, the best approach depends on your income, asset value, and total debt. This guide covers the five primary legal pathways: repayment schemes, voluntary arrangements, the personal bankruptcy process, credit counselling, and debt consolidation plans. IRB Law LLP provides the expert legal guidance needed to navigate these complex financial decisions effectively.
Debt Repayment Scheme
A debt repayment scheme is a structured plan where a debtor agrees to pay a portion of their debt over a fixed period. This approach is often the first step for individuals who have a stable income but are currently overwhelmed by high monthly interest rates. The goal is to reduce the total cost of the debt while maintaining the debtor's credit standing.
How the Scheme Works
When to Use a Repayment Scheme
This option is best suited for individuals who have a clear path to financial recovery. If you have a job and a predictable income, a repayment scheme can help you clear your debts without the severe legal consequences of bankruptcy. IRB Law LLP can assist in reviewing these agreements to ensure they are fair and legally binding.
Voluntary Arrangements
A voluntary arrangement is a formal agreement between a debtor and their creditors to restructure the debt. Unlike a simple repayment scheme, a voluntary arrangement is legally binding once approved. It allows the debtor to propose a plan for repaying a percentage of the debt over a specific timeframe. according to Chapter 13 bankruptcy
The Legal Framework
In Singapore, voluntary arrangements are governed by the Insolvency, Restructuring and Dissolution Act (IRDA). This legal framework provides a structured environment for debtors to negotiate with their creditors. The arrangement must be approved by a majority of the creditors to be enforceable in court.
Benefits of Voluntary Arrangements
One of the primary benefits is that it prevents the debtor from being declared bankrupt. It also allows the debtor to retain control over their assets. However, the process requires transparency and cooperation from all parties involved. Legal advice is essential to ensure the arrangement meets all statutory requirements.
Personal Bankruptcy Process
Personal bankruptcy is a legal status declared by the High Court of Singapore to an individual who is unable to repay debts amounting to $15,000.00 and up. When a person is made bankrupt, an Official Assignee is appointed to manage their estate. This is a serious legal step that should only be considered when other options have failed.
Eligibility and Petitioning
According to Section 61 of the Bankruptcy Act, a creditor can file a petition if the debtor owes more than S$15,000. The debtor must have property in Singapore or have resided or carried on business in Singapore within the year preceding the filing. If the court is satisfied that the debtor cannot pay their debts, a bankruptcy order will be issued.
Life as a Bankrupt
Once declared bankrupt, the individual faces several restrictions. They cannot leave Singapore without permission, cannot act as a company director, and must surrender their assets to the Official Assignee. The Official Assignee investigates the bankrupt's affairs and distributes their assets to creditors. This process can last for several years until the individual is discharged.
Credit Counselling in Singapore
Credit counselling is a service provided by licensed agencies to help individuals manage their debts. In Singapore, the Monetary Authority of Singapore (MAS) regulates these agencies to ensure they provide ethical and effective advice. Credit counsellors work with debtors to create a budget and a repayment plan.
Role of Licensed Agencies
Licensed credit counselling agencies in Singapore offer free or low-cost advice to individuals. They help debtors understand their financial situation and explore options for debt restructuring. These agencies often work with banks to negotiate better terms for the debtor. It is important to choose an agency that is licensed by MAS to ensure you receive professional and unbiased advice.
When to Seek Counselling
Credit counselling is recommended for individuals who are struggling to manage their monthly expenses. It is a proactive step that can prevent a situation from escalating to bankruptcy. IRB Law LLP often recommends that clients seek credit counselling as a first step before considering legal action.
Debt Consolidation Plan
A debt consolidation plan is a financial strategy where multiple debts are combined into a single loan. This simplifies the repayment process by replacing several high-interest debts with one lower-interest loan. It is a common tool for individuals who have accumulated debt from various sources such as credit cards and personal loans.
How Consolidation Works
Under a consolidation plan, the debtor takes out a new loan to pay off all existing debts. The new loan usually has a lower interest rate and a longer repayment period. This reduces the monthly payment amount, making it easier for the debtor to manage their finances. However, it is important to ensure that the total cost of the new loan is lower than the sum of the original debts.
Risks of Consolidation
While debt consolidation can be helpful, it also carries risks. If the debtor continues to borrow against the new loan, they may end up with even more debt. It is essential to address the underlying causes of the debt, such as overspending or lack of budgeting. Legal and financial advice should be sought before entering into a consolidation plan.
Comparison of Debt Restructuring Options
| Option | Best For | Legal Consequence | Asset Impact |
|---|---|---|---|
| Debt Repayment Scheme | Stable income, high interest | None | None |
| Voluntary Arrangement | Multiple creditors, no bankruptcy | Legally binding agreement | Retained by debtor |
| Personal Bankruptcy | Debt over $15,000, no assets | Bankruptcy order | Assets surrendered |
| Credit Counselling | Early-stage debt issues | None | None |
| Debt Consolidation | Multiple high-interest loans | New loan agreement | May require collateral |
Key Takeaways
- Debt restructuring is a legal process to renegotiate repayment terms to avoid insolvency.
- A debt repayment scheme is best for individuals with stable income and high interest rates.
- Voluntary arrangements are legally binding agreements governed by the IRDA.
- Personal bankruptcy is declared by the High Court for debts of $15,000 or more.
- Credit counselling is a regulated service that helps individuals manage their debts.
- Debt consolidation combines multiple debts into a single loan with a lower interest rate.
- It is essential to seek legal advice before choosing a debt restructuring option.
- IRB Law LLP provides expert guidance on all aspects of debt restructuring and bankruptcy.
Frequently Asked Questions
What is the minimum debt amount for personal bankruptcy in Singapore?
According to the Bankruptcy Act, a creditor can file a petition if the debtor owes more than S$15,000. The debtor must also have property in Singapore or have resided or carried on business in Singapore within the year preceding the filing.
Can I avoid bankruptcy by using a voluntary arrangement?
Yes, a voluntary arrangement is a legal alternative to bankruptcy. It allows the debtor to propose a plan for repaying a percentage of the debt over a specific timeframe. The arrangement must be approved by a majority of the creditors to be enforceable in court.
What happens to my assets if I am declared bankrupt?
When a person is made bankrupt, an Official Assignee is appointed to manage their estate. The Official Assignee investigates the bankrupt's affairs and distributes their assets to creditors. The bankrupt must surrender their assets to the Official Assignee.
Is credit counselling free in Singapore?
Licensed credit counselling agencies in Singapore offer free or low-cost advice to individuals. It is important to choose an agency that is licensed by MAS to ensure you receive professional and unbiased advice.
How does debt consolidation work?
Under a consolidation plan, the debtor takes out a new loan to pay off all existing debts. The new loan usually has a lower interest rate and a longer repayment period. This reduces the monthly payment amount, making it easier for the debtor to manage their finances.
Can I leave Singapore if I am bankrupt?
No, once declared bankrupt, the individual faces several restrictions. They cannot leave Singapore without permission from the Official Assignee. They also cannot act as a company director and must surrender their assets to the Official Assignee.
Conclusion
Navigating debt restructuring and personal bankruptcy in Singapore requires a clear understanding of your legal options. Whether you choose a repayment scheme, a voluntary arrangement, or a debt consolidation plan, the goal is to achieve financial stability. IRB Law LLP is committed to providing you with the expert legal guidance you need to make informed decisions. Our team of experienced lawyers can help you evaluate your situation and recommend the best course of action. To discuss your options, today for a confidential consultation.